
August was quiet but concentrated. My Cyber Market Intelligence log captured 65 verified events across ~$6.6B of deal value - yet two prints are ~70% of that: BioCatch's $2.4B sale to Visa and Cloudflare's $2.2B post-IPO debt raise. Strip those and it's a summer-slow ~$2B month, with deal count down sharply from July (~93 → 65 events). What did not slow was where the money pointed: agentic AI, on both sides of the wire. AI Security was the only segment up on both count and dollars; identity took the biggest checks; offensive security was the fastest accelerant market-wide. For outside context, ROS put trailing-month cyber financing at $3.31B across 29 rounds plus $1.39B across 33 M&A deals (market-wide). Cyber capital is consolidating around AI - quietly but decisively.
Key drivers this month
AI Security is the only segment up on both axes - 15 deals / $533M (CMI) vs ~11 / ~$508M in July. ROS independently ranks AI for Security at +28% deals, +110% funding vs prior period (market-wide). Alice $140M, Zenity $125M, Obsidian $85M, Corma $60M (Sequoia seed) - all landed in August.
Identity ate the biggest checks - IAM booked $2.56B across just 4 events: BioCatch $2.4B → Visa and Socure’s $156M growth round at a $5.2B valuation, alongside its acquisition of agentic fraud-ops platform Fravity.
Offensive/validation security is the sharpest accelerant - ROS flags Offensive Security at +77% deals, +1,073% funding vs prior period (market-wide). In-pipeline, Horizon3.ai raised $250M Series E at a $2B valuation - autonomous pentest at scale.
Services consolidation kept grinding - 19 events / $820M, led by Munich Re → At-Bay $575M and ScanSource → MicroAge $220.5M. A rollup engine, not new-company formation.
The market map
Twelve segments, ranked by August deal value and classed by momentum vs July (CMI).
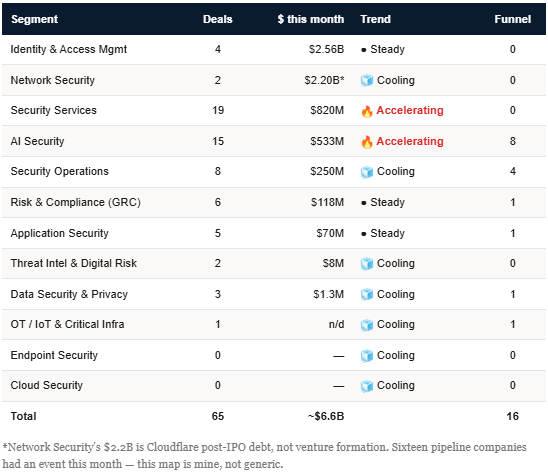
1 - Agentic security is now a budget line
Strip the two mega-prints and AI Security was the deepest pool of new capital in August - 15 rounds, $533M - mapping directly onto my hottest convictions: non-human & agent identity governance, agent evaluation & containment, agentic runtime security, AI agent spend governance. The signal round is Zenity’s $125M Series C (Norwest, SoftBank Vision Fund 2) - agent security governance. Around it: Corma $60M seed led by Sequoia, Obsidian $85M Series D at $1.1B, and a cluster of earlier-stage bets - Arrakis Security ($8M seed), Attestable ($20M seed), Xpander ($7.5M). This is no longer “AI + security” as a label; it’s enterprises funding a distinct control plane for autonomous agents - identity, authorization, runtime containment and spend. Capital and conviction point the same way. The differentiated move is at seed/Series A, where I already have live relationships, before the category’s pricing fully re-rates.
2 - Autonomous offensive security: validate, don’t just scan
The strongest cross-signal this month is offensive security. ROS ranks it the fastest-accelerating category market-wide - +77% deals, +1,073% funding vs prior period (ROS) - lining up with my theses on affordable AI offensive security for the mid-market, AI-vs-AI vulnerability triage, and reachability-based scanner-noise triage. In-pipeline, the anchor is Horizon3.ai’s $250M Series E at a $2B valuation - autonomous pentest moving from point tool to platform, NightDragon and NEA co-leading, Sapphire joining. Underneath it, Cytix raised a $7M Series A for continuous pentesting (Europe), and Brinqa → PlexTrac closed the month’s largest CTEM consolidation - exposure management merging with offensive validation so the “prove it’s exploitable” loop runs continuously. The thesis: buyers are done paying for scanners that generate noise; they’ll pay for systems that demonstrate real, reachable risk. I’m tracking both the scaled leader and an early European challenger - rare coverage across the stack’s price points.
3 - Identity verification consolidates into the payments core
Identity took August’s biggest dollars, and the shape matters more than the size. BioCatch → Visa at $2.4B (behavioral biometrics into the payments core) and Socure’s $156M round at $5.2B - paired with its acquisition of agentic fraud-ops platform Fravity - say the same thing: identity verification is being absorbed into the transaction layer and wired to autonomous case handling (Fravity cut cost-per-case ~80%). Add Alice’s $140M Series D in Israel (Apax Digital, SentinelOne) and Apate.AI’s $8.15M seed for adversarial anti-scam AI, and the category is pivoting from passive verification to active, agent-driven fraud defense - squarely within my verification-in-workflow and deepfake/AI-fraud-defense theses. A pipeline footnote with teeth: Clarity - a tracked name - was acquired by Deel in August. The consolidation is live and reaching companies I already know. The open lane is verification that survives an agent-vs-agent world, upstream of the incumbents now buying their way in.
Closing - emerging & adjacent
Beyond the twelve, three adjacencies are worth watching. Post-quantum crypto is quietly consolidating - Quantumiq → Redwood AI, pQCee → Universal Digital, CyberCatch → Datavault ($94.5M) - as enterprises buy quantum-readiness tooling ahead of mandates. Cyber-physical / defense-tech is crossing over: SAM Seamless Network → Qualcomm, with XTEND’s $1.5B NYSE IPO signalling liquidity for Israeli defense-tech. And AI-native SecOps is where the next platform fight lands - Console → Palo Alto ($500M) and a wave of autonomous-SOC seeds suggest legacy SIEM/SOAR is under sustained pressure. None is a defined segment yet; all three are where the 2026-27 theses will likely form.
F.